01
Compare Paphos and Limassol
Use the official tourism portal to explore regional settings, cultural routes, beaches and visitor information. Then test the routes to the shops, schools and services you will use.
Visit Cyprus
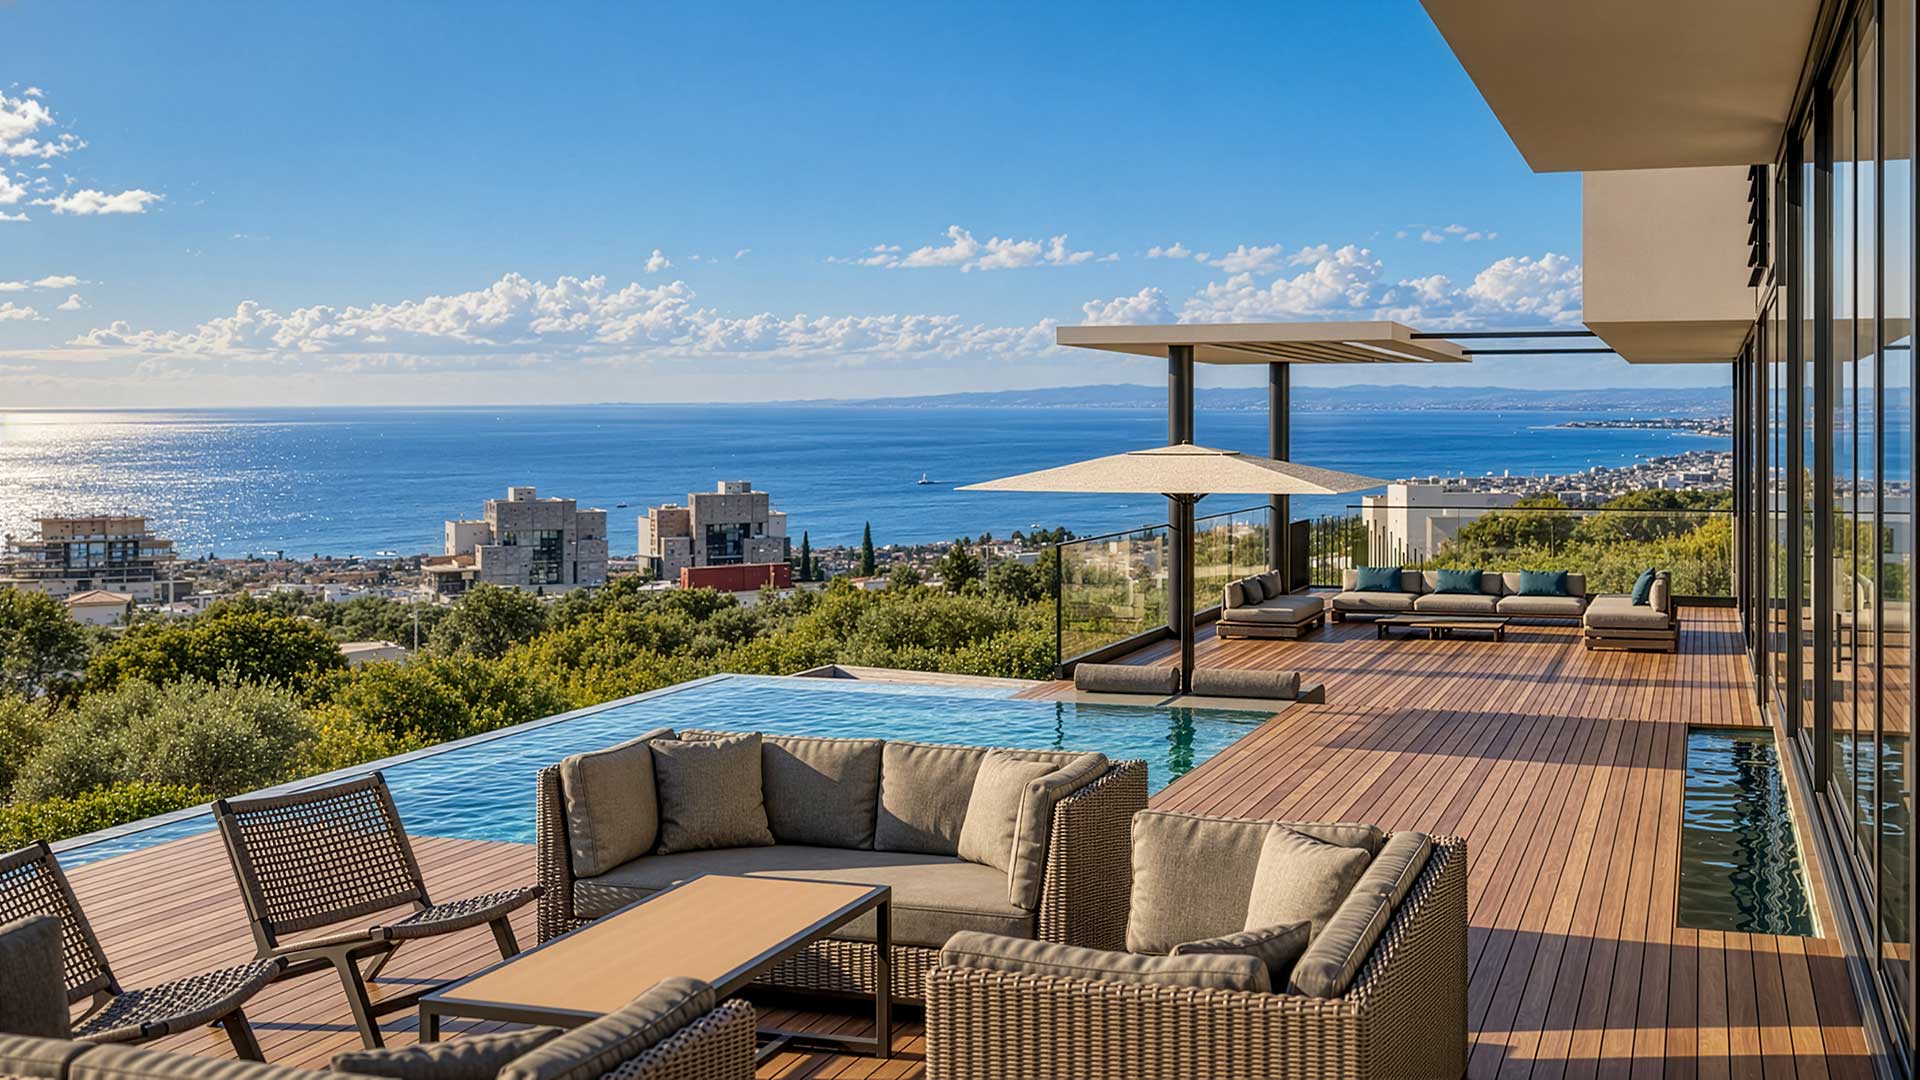
Cyprus property and residency guide
A home in Cyprus can support a lifestyle move, a second-home plan or an investment search. Use this guide to understand the property, residency and tax questions raised in the material supplied to Solara, then check the current requirements with the relevant authorities and your independent advisers.
Explore the portfolio
Cyprus properties
View the current collection and request live availability.
Reviewed
Prepared from the residency and tax material supplied to Solara, with official resources and professional tax references checked on 4 November 2026. Some supplied wording differs from current guidance, particularly on payment evidence, tax residency and VAT transitions; the affected sections explain the current position. General information only, not legal, immigration, tax or investment advice. Obtain independent advice in Cyprus and your home country before committing.
01
The investor residential route starts at €300,000 plus VAT for a qualifying first-sale home, subject to the full programme criteria.
02
The foreign-income test starts at €50,000 annually, with additions for a spouse and eligible dependent children.
03
Residence permission, tax residence and reduced VAT have different conditions. None follows automatically from a purchase.
Area context
These notes are a practical starting point for comparing the places around a home. Follow the source links for current public information, then test the details that matter to you on the ground.
01
Use the official tourism portal to explore regional settings, cultural routes, beaches and visitor information. Then test the routes to the shops, schools and services you will use.
Visit Cyprus02
Non-EU buyers should check the Ministry of Interior’s property-purchase permission process and obtain independent legal advice. Buying permission and immigration approval are separate decisions.
Ministry of Interior03
GESY eligibility depends on residence and the appropriate beneficiary category. Check the official conditions and enrolment process before relying on cover for your household.
GESY eligibility01
For third-country nationals, Regulation 6(2) provides an investor route to an immigration permit. The residential option requires a first-sale house or apartment bought from a development company, worth at least €300,000 plus VAT. A resale home does not qualify under this residential category except for the narrow historical exception in the official policy.
The Migration Department requires official receipts showing at least €300,000 paid excluding VAT when the application is submitted, regardless of delivery date. The investment funds must be evidenced as coming from abroad. This corrects the €200,000 payment wording in one supplied guide; it does not mean the full price of every higher-value home must already be paid.
For this residential route, secured annual income from abroad must be at least €50,000. The requirement rises by €15,000 for a spouse and €10,000 for each dependent minor child; the spouse’s income may count. Clean criminal records, health insurance and the other quality criteria also apply. The permit does not grant a general right to take paid employment, although the policy contains limited director and shareholding exceptions.
The main permit covers a spouse and children under 18. Unmarried, financially dependent children between 18 and 25 studying tertiary education abroad may apply separately under additional conditions. Do not assume all adult children or parents are covered. Ask an immigration lawyer to check the investment and each family member before reserving a home.
02
The official policy describes an unlimited residence right for the holder and adult dependants, but the physical adult residence card expires after ten years and must be replaced. Applicants living abroad must acquire residence in Cyprus within one year of approval. Permanent residence abroad or an absence from Cyprus for two years can end the permit. A simple promise of validity for life leaves out these obligations.
Current official clarifications require annual evidence that the qualifying investment is maintained, and health-insurance evidence where the family no longer benefits from GESY. Adult criminal-record certificates are required every three years. The earlier annual income-evidence requirement was abolished. Confirm the current filing checklist and any proposed sale or replacement investment with your lawyer; neither approval nor a processing deadline is guaranteed.
03
The standard Cyprus VAT rate is 19%. Under the general reduced-rate scheme, eligible buyers using a qualifying home as their main residence can apply for 5% VAT on the first 130 m² of buildable area up to a value of €350,000. The total transaction value must not exceed €475,000 and the total buildable area must not exceed 190 m². Special and transitional cases need separate checks; 5% is not a blanket rate for every home.
The main-residence requirement runs for ten years. Letting the home or changing its use can affect relief and may trigger a proportional repayment, subject to the applicable rules and exceptions. A property suitable for the residency programme is not automatically eligible for reduced VAT. Do not assume a buy-to-let or occasional holiday home qualifies.
Older planning applications may fall under a different transitional scheme using 200 m². KPMG’s May 2026 report of the Tax Department announcement describes a conditional extension to 31 December 2026, not a universal extension: planning-application and building-permit dates matter. The unqualified 200 m² wording in the supplied programme should not be used for a new purchase without checking those dates. Obtain a written assessment of the specific property from your Cyprus tax adviser.
04
A residence permit does not itself make you Cyprus tax resident. The 183-day rule generally requires more than 183 days in Cyprus in a calendar year. The separate 60-day rule requires at least 60 days in Cyprus, no more than 183 days in another single country, specified Cyprus business, employment or company-office ties, and an owned or rented permanent home. All the relevant conditions must be met.
The requirement to be tax resident in no other country was removed from the 60-day test from 1 January 2026. One supplied guide still contains that older condition. Other countries can nevertheless treat you as tax resident, and treaty rules may matter. Ask advisers in both countries to review your day counts, income, family ties and any dual-residence position.
The business or employment connection needed for a tax test must also be compatible with the conditions of your immigration permit. Do not assume that a tax-residence route gives you permission to work in Cyprus.
05
Cyprus tax residents are generally taxed on worldwide income, while non-residents can still owe Cyprus tax on relevant Cyprus-source income. For 2026, the first €22,000 of chargeable personal income falls within the zero-rate band. This is an income-tax band, not an automatic exemption for a property purchase or all overseas income.
Special Defence Contribution on rental income was abolished from 1 January 2026. Rent is not therefore tax-free: ordinary income tax can still apply, and General Healthcare System contributions may also be due. Ask your adviser to check the ownership structure, allowable costs, rental use and obligations in your home country before comparing income after costs.
Non-dom status concerns domicile for Special Defence Contribution and can exempt qualifying individuals from that contribution on dividends and interest. It is not a blanket exemption from income tax, property capital-gains tax or healthcare contributions. The deemed-domicile rules include tax residence in at least 17 of the previous 20 years. Eligibility and any extension provisions require individual advice; buying a home alone does not establish this status.
06
Purchase VAT and Land Registry transfer fees are different charges. The current tax reference states that no transfer fees are payable where VAT applies to the purchase; where VAT does not apply, the ordinary transfer-fee scale is reduced by 50%. Legal work, financing, registration and other expenses can still arise. Obtain a written cost estimate for the specific transaction.
The national immovable property tax was abolished from 2017, but municipal charges, refuse and sewerage costs, insurance, maintenance and shared-service costs can still be relevant. Cyprus property gains can be subject to capital-gains tax at 20%, with allowable costs and conditional exemptions. Non-dom status does not by itself remove this liability. Plan the tax and costs of both ownership and sale with your advisers.
07
The Ministry of Interior states that non-EU nationals and certain foreign-controlled companies need local District Administration permission to acquire immovable property. This is separate from immigration approval. Ask an independent lawyer to check title deeds, mortgages and other encumbrances, planning and building permissions, the sale contract and transfer conditions. For off-plan homes, confirm the written specification, delivery position and purchase stages.
Use the Deputy Ministry of Tourism’s Visit Cyprus portal to compare Paphos, Limassol and surrounding villages, then test the actual journeys to schools, shops and medical services. An attractive render does not establish included furnishings, a guaranteed view or everyday convenience.
GESY healthcare eligibility depends on residence in the Republic’s government-controlled areas and the relevant beneficiary category. A property purchase is not enrolment. Check eligibility, registration and any private insurance required before moving, alongside school places, utilities and ongoing household costs.
Viewing prompt
A polished brochure cannot answer every practical question. Use viewings to compare the location against the daily life you are planning.
Check 01
Test everyday routes to shops, schools, medical services and the airport. Revisit the area outside peak holiday periods if possible.
Check 02
Ask an independent lawyer to check title, permissions and written purchase terms. Confirm the home’s intended use, VAT position and complete ownership costs before reserving.
Check 03
Prepare separate immigration, tax and healthcare checks for each household member. Confirm the investment, payment evidence, income and continuing obligations with qualified advisers.
Purchase rules, ownership structures, taxes, foreign-exchange exposure, financing options and buyer protections can differ materially between countries. Ask for current local documentation and seek independent legal, tax and financial advice in the relevant jurisdiction before proceeding.
No. Property ownership and residence permission are separate processes. The investor residential route requires a qualifying first-sale property worth at least €300,000 plus VAT, together with payment evidence, sufficient foreign income and the other applicant conditions. Approval is not guaranteed. Ask an independent Cyprus immigration lawyer to assess your household before committing.
No. Reduced VAT is conditional on a qualifying main residence, area and value limits, and the relevant application rules. A buy-to-let or holiday home does not automatically qualify. Older transitional cases have different conditions. Obtain a written, property-specific VAT assessment from an independent Cyprus tax adviser before budgeting for relief.
No. Immigration permission, tax residence, domicile and healthcare eligibility have separate conditions. Confirm Cyprus and home-country tax obligations with qualified advisers. Check GESY eligibility and registration before relying on healthcare cover. A property purchase is not automatic tax-resident status or healthcare enrolment.
Continue reading
London market guide
Explore a practical starting point for searching London property, from neighbourhood fit and connectivity to verifying a development’s current details.
Manchester market guide
A practical guide to approaching a Manchester property search, with a focus on city-centre living, neighbourhood context and current development information.
Birmingham market guide
Use this guide to frame a Birmingham property search around location, property type, transport and development details that need verification.
Personal search
Tell us what you are looking for and we can help bring the relevant property opportunities into focus.